Categories List
 China Customs Launches Smart Preclassification Channel for Coatings ExportsAug 16, 2026
- China Customs Launches AI Preclassification Channel for Paint ExportsAug 15, 2026
- 越南要求进口工业涂料提交SVHC声明Aug 14, 2026
- China Customs Opens Smart Pre-Review for Coating ExportsAug 13, 2026
- EU REACH Limits NMP in CoatingsAug 13, 2026
- Shenzhen Fluorosilicone Expo Opens in October 2026Aug 12, 2026
Leave A Reply
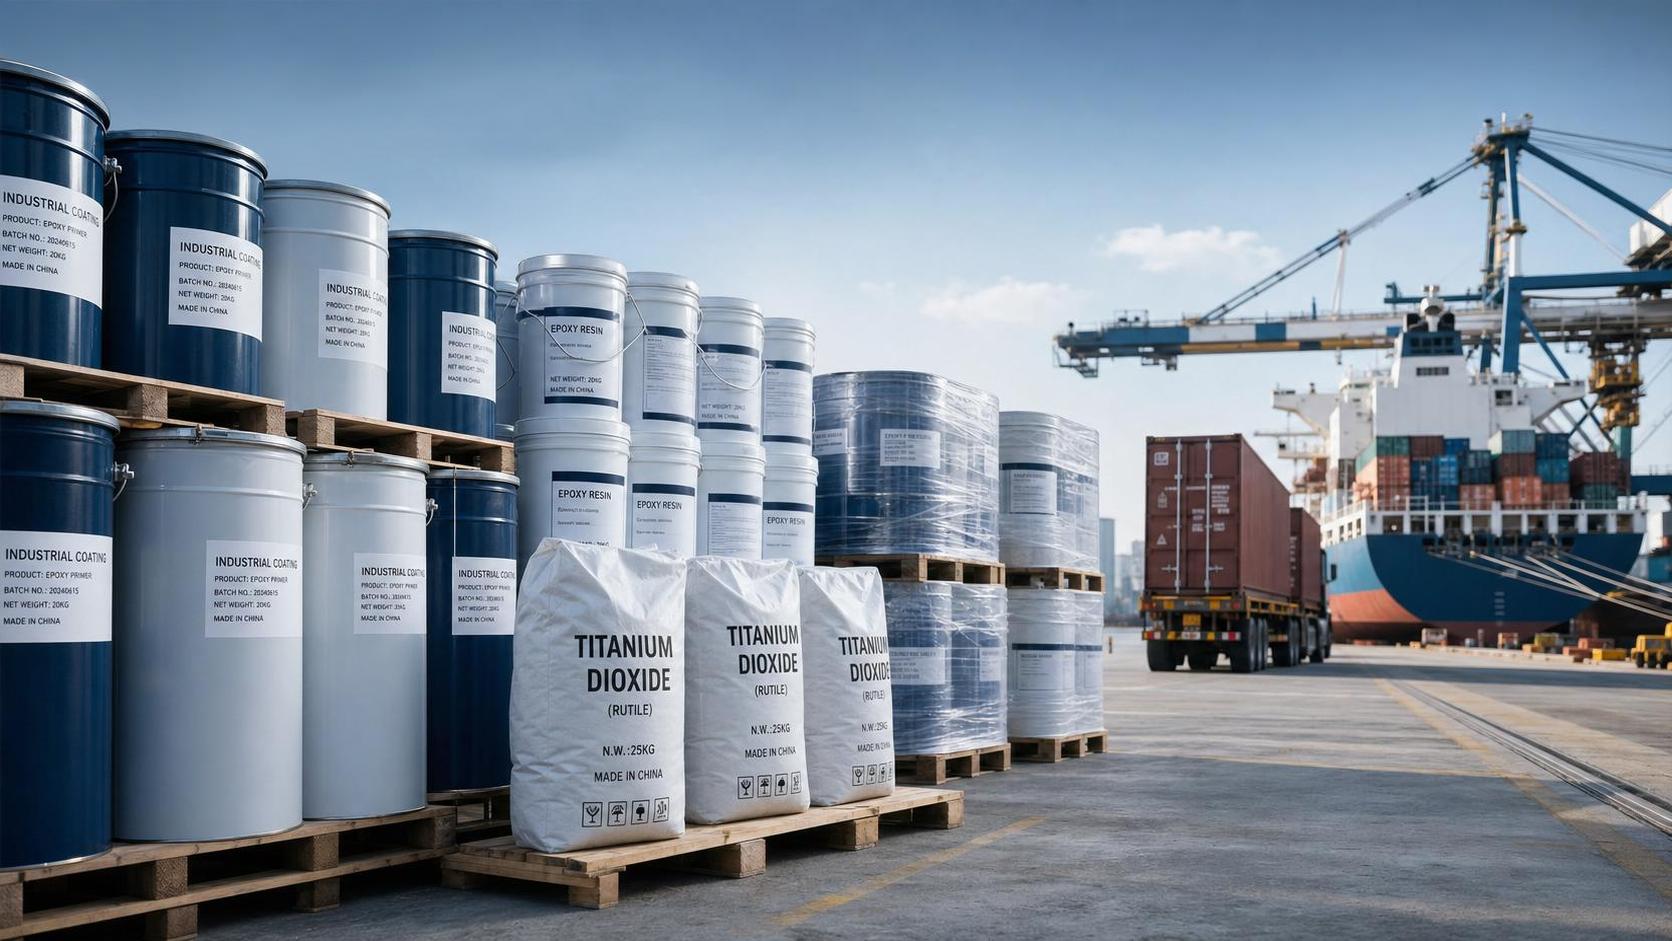
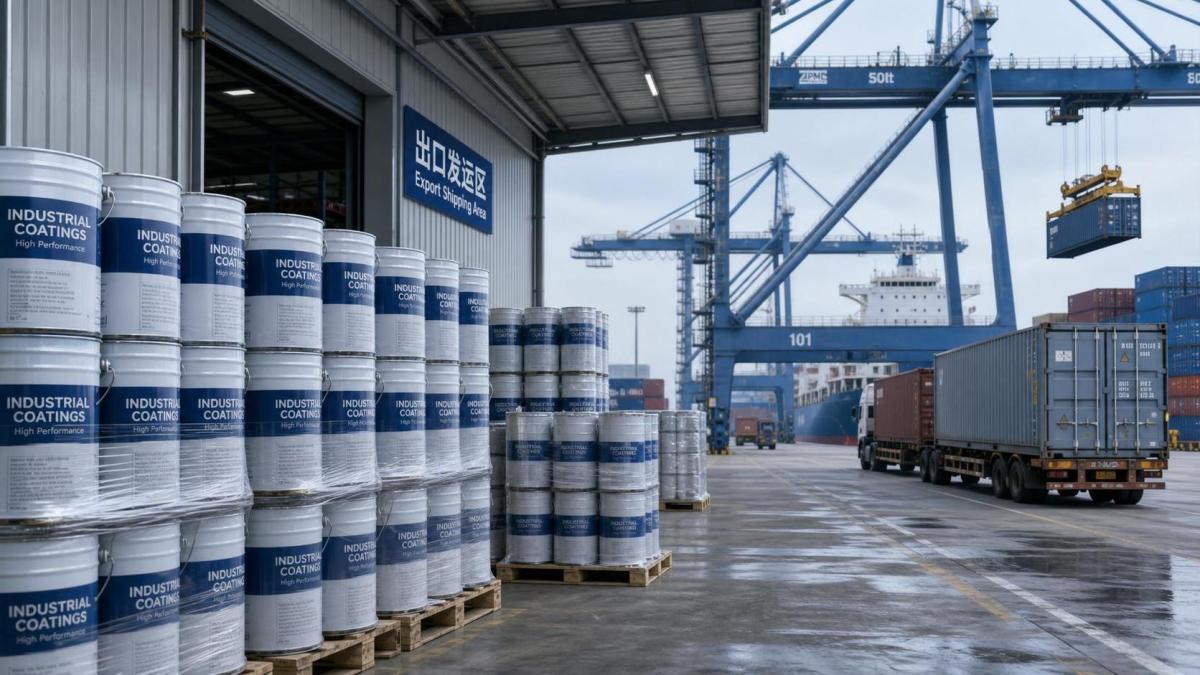
Between April 1 and June 30, 2026, China’s export lead time for high-performance industrial coatings moved out to 6-8 weeks, signaling a practical shift in delivery expectations for cross-border trade rather than a routine market fluctuation. The change matters because it affects procurement planning, FOB shipment scheduling, and contract execution for exporters, overseas buyers, and supply-chain service providers working with industrial coatings bound for Middle East and Southeast Asia markets.
What Has Been Confirmed in Q2 2026
According to CCCME, the average lead time for export orders of high-performance industrial coatings increased to 6-8 weeks in Q2 2026, compared with 4-5 weeks in Q1. The stated reason is constrained supply of titanium dioxide and epoxy resins. At the same time, ports in Ningbo and Qingdao reported container allocation delays, which affected FOB delivery schedules for buyers in the Middle East and Southeast Asia.
Where the Pressure Is Likely to Show Up First
Export scheduling is becoming harder to lock in
From an industry perspective, export traders and coating manufacturers are likely to feel the impact first in order confirmation, production sequencing, and shipment booking. When average lead times extend from 4-5 weeks to 6-8 weeks, the operational issue is not only slower factory release but also greater pressure on promised FOB timelines.
Procurement teams face tighter material and delivery coordination
Analysis shows that companies buying titanium dioxide- and epoxy resin-dependent coating products may need to pay closer attention to purchase timing, supplier confirmations, and delivery clauses. The immediate concern is whether procurement plans, tender schedules, or project supply windows still match the longer export cycle now being reported.
Logistics providers must watch port-side execution risk
For freight forwarders and other supply-chain service providers, the reported container allocation delays in Ningbo and Qingdao point to a transport-side constraint that can affect FOB execution even after production is ready. What deserves closer attention is the coordination between factory completion dates and actual container availability.
Overseas buyers may need stricter document and delivery alignment
Buyers in Middle East and Southeast Asia markets are likely to be affected in delivery planning and contract management. Observably, where FOB schedules become less predictable, purchase orders, shipment windows, and supporting trade documents may require closer review to reduce disputes linked to delayed handover timing.
What Companies Should Monitor Now
Review whether contract timing still reflects current lead times
Analysis shows that exporters and buyers should recheck whether existing order lead times, shipment commitments, and FOB milestones still reflect the Q2 situation described by CCCME. This is especially relevant for transactions that were planned using Q1 delivery assumptions.
Track procurement exposure tied to key raw materials
What deserves closer attention is the degree to which current export orders depend on titanium dioxide and epoxy resins. The available information does not establish a formal rule change, but it does indicate a supply condition that may alter how companies assess sourcing reliability and delivery risk.
Watch for execution language in trade and tender documents
From an industry perspective, firms should pay attention to how delivery periods, shipment terms, technical documentation, and order confirmation language are being handled in active negotiations. Where input materials and container allocation are both under pressure, document consistency becomes more important for trade execution and later claims handling.
Keep following any updated market or association signals
The current information supports closer monitoring rather than a definitive conclusion about longer-term supply conditions. Companies should therefore continue watching for updated wording, implementation signals, or operational guidance from relevant trade and industry channels before treating the Q2 pattern as a stable baseline.
Why This Looks More Like an Execution Signal Than a Formal Rule Change
Observably, the reported extension in export lead times does not by itself establish a new regulation, certification rule, or formal trade restriction in the materials provided. It is more appropriate to understand this as an execution-level signal affecting delivery discipline, procurement timing, and FOB performance. Analysis shows that this kind of signal matters because buyers and sellers often experience rule pressure through shipment practice and contract performance before any broader policy interpretation becomes clear.
How the Market May Need to Read This Development
The industry significance of this update lies in its effect on day-to-day trade execution. A longer lead time, combined with container allocation delays at Ningbo and Qingdao, suggests that industrial coatings exporters and overseas buyers may need to treat delivery planning with more caution in the near term. At present, it is more appropriate to read this development as a market execution change that deserves continued observation, rather than as a fully defined regulatory shift with settled outcomes.
Basis of This Article and What Still Needs Verification
This article is based on the user-provided news title, event period, and summary. Source types commonly relevant to developments of this kind may include official notices, regulator releases, customs or trade authority information, industry association updates, standards documents, and reporting from authoritative trade media. No specific official source link was provided in the input, so further verification is still required. What should continue to be monitored includes any later policy detail, execution wording, certification or compliance interpretation, tender document changes, market feedback, and how companies are handling delivery in practice.